
UK State Pension Age Rises Again Amid Rate Shock
British households face a double-barreled economic shift this season. As the official UK State Pension age advances on its scheduled path from 66 to 67, millions of workers find their retirement horizons subtly slipping further into the distance. Simultaneously, borrowing costs across the high street have surged, pushing fixed mortgage products to three-year highs and complicating financial calculations for homeowners and hopeful buyers alike.
The UK State Pension age is currently transitioning from 66 to 67 between 2026 and 2028, with a statutory move to 68 scheduled by 2046. The ongoing State Pension Age Review is evaluating whether demographic shifts and life expectancy trends warrant accelerating or modifying this timeline.<\/p>
- Retirement Age Advance: The statutory transition from age 66 to 67 for the UK State Pension age is officially underway, with an independent review evaluating a potential move to 68 earlier than 2046.
- Mortgage Repricing Pressure: Average fixed mortgage rates have reached a three-year peak, significantly squeezing households seeking new deals or initial home purchases.
- Broadband & Wildlife Currency: The Bank of England has unveiled popular wildlife choices—including the hedgehog and barn owl—for its next banknote series following a major public consultation.
- Pioneering Legacy: Personal finance broadcasting mourns the passing of Louise Botting, former presenter of BBC Radio 4's Money Box, who spent decades championing consumer rights.
Economic headwinds are rarely polite enough to arrive one at a time. While personal finance spreadsheets are being redrawn across the country, policy experts are wrestling with long-term demographic balance sheets. The modern welfare state is bumping up against cold, hard actuarial mathematics, leaving ministers with few easy choices.
Moving the Goalposts: Inside the UK State Pension Age Shift
The transition currently taking shape is not a surprise, yet its arrival carries immediate consequences. Legislation passed years ago established that the qualifying threshold would rise incrementally to 67 between 2026 and 2028. For workers currently in their early sixties, the finish line has officially moved. What used to be a predictable milestone at 65, and then 66, is now firmly set at 67 for those born after April 1960.
Yet the bigger question troubling Westminster policy circles is not 67—it is what comes next. By existing statute, the threshold will climb again to 68 between 2044 and 2046. However, independent reviews retain the power to disrupt that timetable. The third official State Pension Review is actively assessing whether existing legislative assumptions match modern mortality tables and fiscal realities.
Demographics, Life Expectancy, and Fiscal Tension
At the center of this evaluation is Dr Suzy Morrissey, appointed by the Secretary of State for Work and Pensions to deliver an independent report on how future retirement boundaries should be calibrated. The core dilemma is straightforward yet politically explosive: life expectancy gains, which steadily climbed for decades, have plateaued in recent years, particularly across lower-income socio-economic groups.
“Determining the qualifying age for state support is a tightrope walk between long-term public spending sustainability and economic fairness across diverse populations.”
If average life expectancy is no longer expanding at the historical rate seen when earlier pension acts were drafted, automatically raising the threshold penalizes those in physically demanding trades or regions with lower life expectancies. Conversely, maintaining an earlier retirement threshold creates staggering fiscal commitments for future taxpayers as the overall ratio of retirees to active workers grows wider. Industry analysis from Reuters economic reporting highlights how sovereign debt burdens constrain government flexibility when funding non-contributory welfare entitlements.
Mortgage Rate Shock: Navigating Three-Year Highs
While future retirees calculate their working years, active borrowers are contending with an immediate cash-flow strain. Average mortgage rates hit three-year peaks this month, dealing a sharp blow to the roughly 1.5 million households coming off ultra-low fixed-rate arrangements. The days of sub-2% borrowing are firmly in the economic rearview mirror.
For first-time buyers, the hurdle is two-fold. High borrowing costs restrict borrowing capacity relative to income, while sustained real estate valuations demand sizable equity deposits. Meanwhile, existing homeowners facing product expiration must choose between committing to fixed arrangements at modern rates or floating on variable terms in hopes of central bank rate cuts.
Practical Steps for Impacted Homeowners
Financial advisers urge proactive planning rather than waiting for deal expiry dates to force a decision:
- Lock in deals early: Most high-street lenders allow borrowers to secure product transfers up to six months before their current term ends, offering a safety net against further rate hikes.
- Audit household outgoings: Trimming non-essential commitments months ahead improves affordability scores during lender stress testing.
- Explore overpayments: Even modest overpayments during an existing low-rate fix directly reduce capital balances, dampening the hit when re-contracting at higher yields.
- Consult independent brokers: Broker networks often access specialist sub-prime or niche building society rates that are unavailable on general comparison tables.
Comparative Overview: Mortgage and Pension Metrics
To contextualize these economic shifts, the table below outlines structural metrics across mortgage pricing trends and state pension timeline milestones over recent reporting periods.
| Metric / Dynamic | Historical Baseline (2021) | Previous Benchmark (2023–2024) | Current Snapshot (Late 2026) |
|---|---|---|---|
| State Pension Age Threshold | 66 Years | 66 Years | Transitioning to 67 |
| Statutory Target for Age 68 | 2044–2046 Target | Under Active Review | Review Pending Decision |
| 2-Year Fixed Mortgage Average | 1.85%–2.20% | 4.50%–5.20% | Three-Year High Peak |
| Primary Driver of Policy Shift | Post-pandemic recovery | Inflationary pressure | Demographic adjustment & persistent rates |
A Voice That Demystified Personal Finance: Remembering Louise Botting
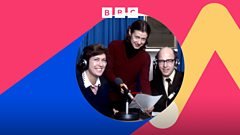
Amid the modern debate over yields and pension formulas, the personal finance community mourns a monumental figure who spent her career making such complexities understandable to the general public. Louise Botting, the legendary former presenter of BBC Radio 4’s Money Box, has died at the age of 87 following a short illness.
Botting was a pioneer in financial broadcasting. Joining Money Box at its inception in 1977, she fundamentally altered how mainstream audiences consumed money news. At a time when banking, insurance, and taxation were guarded by archaic terminology and institutional gatekeeping, Botting brought a tenacious, consumer-first approach to the airwaves.
She held institutional leaders accountable, questioned complex bank charges, and demystified tax obligations for millions of listeners every weekend. Her broadcaster legacy created the template for modern consumer journalism, proving that everyday citizens could—and should—take command of their personal balance sheets.
Prickles and Wings: Banknotes Get a Wildlife Overhaul
In a rare intersection of civic engagement and currency design, the Bank of England has confirmed the animal species that will feature on the next generation of UK banknotes. Following an extensive national consultation that saw nearly 500,000 citizens cast votes, four native species were selected: the hedgehog, the barn owl, the puffin, and the bumblebee.
The decision reflects a broader cultural shift toward recognizing native biodiversity within national iconography. While physical currency usage has declined relative to digital payments, paper and polymer bills remain critical financial infrastructure and expressions of national heritage. Detailed design renders from central banking sources show how intricate wildlife illustrations will sit alongside standard security elements, security threads, and tactile features for the visually impaired.
Broader coverage from Bloomberg financial indicators notes that symbolic currency updates often coincide with wider central bank efforts to refresh physical security features against sophisticated counter-feying networks.
What Lies Ahead for British Pocketbooks
Navigating the current financial climate requires both immediate tactical adjustments and long-term strategic patience. The simultaneous pressures of high borrowing costs and an advancing pension threshold illustrate a broader structural truth: reliance on automatic state protections or legacy mortgage rates is no longer a viable strategy for financial security.
Whether managing monthly home loan obligations, evaluating investment strategies in light of a changing retirement target, or simply keeping pace with economic shifts, proactive financial literacy remains the single most effective tool for household resilience. The rules of the financial game are changing—and keeping informed is the only way to adapt successfully.
<button type="button" onclick="this.parentElement.innerHTML='✓ Thank you, we will refine our analysis!‘” style=”background:#ffffff; border:1px solid #cbd5e1; border-radius:6px; padding:4px 12px; font-size:12px; cursor:pointer; color:#334155;”>👎 No
Latest Analytical Follow-up: For continuous developments on this subject, read our full investigation on Roofing scammers con homeowners out of thousands of pounds.
Latest Analytical Follow-up: For continuous developments on this subject, read our full investigation on Escalating Costs: The Real Price of Bad Debt Advice.
